by SFT | Oct 11, 2026 | Financial Planning, St Francis
This week I was meant to be in Cape Town for the Financial Planning Institute’s annual convention. It’s an event I look forward to every year. It’s a chance to learn, and to reconnect with people I’ve come to know over 35 years in financial services.
Then life happened.
A very dear friend, someone I met through this industry, passed away from cancer. His diagnosis came five years ago and forced him into retirement. He was about to turn 69. I have never known a better or kinder man and saying goodbye to him was never something I would miss. So, I missed the first day of the convention. After the funeral I headed straight to the airport and flew to Cape Town for day two.
When I landed and switched on my phone, I saw a missed call from a client I have worked with for more than 25 years. I called him back right away, and I could hear immediately that something was wrong. He wanted to meet, he said, to “get something off my chest.”
My mind raced. What had happened? Had I done something wrong?
Then he said, “Okay, well, let me tell you. I’ve been diagnosed with lung cancer.”
I stopped dead in my tracks. This is a man who didn’t smoke, and who at 74 was as healthy as anyone I know.
To the man in the street, financial planning is about numbers, markets and returns. Those things matter, of course. But if we do our work as well as we can, it is mostly about people. Over the years we build real relationships, and that means we come to care deeply about the families we work with. The work becomes personal. Usually that is the best part of the job, and sometimes it is the hardest.
Weeks like this one leave me grateful. I’m grateful for the work I ended up doing to feed my family, and I’m aware of what a privileged career I have lived. I know many people view our industry negatively. But I also know how important this work is to the families we serve, especially when life can turn on a single phone call.
At Client Care, we don’t just run the numbers, and we don’t chase the best returns. We do everything we can to help our clients live the best life possible with what they have.
This is meant to be an article about financial advice, so the advice today is: none of us knows when our time is up. So in the end, what matters most is living each day the way we choose by design and not on remote.
Dirk Groeneveld, Certified Financial Planner
t. 083 261 9287
e. dirk@clientcare.co.za
An Investment Portfolio Without a Plan is Meaningless
Five Dangers Of DIY Financial Planning
Finding The Delicate Balance In Giving
Dead Money, Living Money
—

Disclaimer:
This article is for information purposes only and does not constitute financial advice in any way or form. It is important to consult a financial planner to receive financial advice before acting on any information contained herein. Client Care and PWM and its directors, officers, and employees shall not be responsible and disclaim all liability for any loss, damage (whether direct, indirect, special or consequential) and/or expense of any nature whatsoever, which may be suffered as a result of, or which may be attributable, directly or indirectly, to the use of, or reliance upon any information contained in this article.
by SFT | Oct 4, 2026 | Financial Planning, St Francis
A few weeks ago, we at Client Care hosted a breakfast with my good friend Dan Haylett, a financial planner from London. Dan and I share a passion for helping clients live a full and meaningful retirement. He has written a book on the subject and has just been commissioned by a major European publisher to write another. Our conversation centred on something we both believe needs far more airtime: the tough move from working to retiring, and from saving to spending.
After decades of diligent saving, many retirees find it remarkably hard to switch gears. Where we differ from many advisers is that we encourage our clients to spend their savings rather than hoard them out of fear of running out.

Participation was wonderful, and the range of responses fascinated me, from a sense of helplessness to raw excitement.
Returning from a few weeks out of town, I chatted with some friends who had attended. One was blown away to hear two financial planners advocating spending, especially as a planner’s income is often linked to the assets we advise on. He had been nursing a little buyer’s remorse over a new car, but after the talk felt completely at peace with it, and even topped up the family holiday account for the children and grandchildren.
Another had recently skipped a family get-together at a wine farm, worried about what the day would cost him. He regrets it now, and says he won’t make that mistake again.
Then there was the wife of a client retiring in a few months. She came over with a smile and told me I had my work cut out shifting her husband out of the saving mindset, the very habit that has allowed them to retire so comfortably.
I’ll admit I was a little nervous building a talk around the soft stuff rather than markets and tax strategies. The response has shown me that the soft stuff is actually the hard stuff, and it’s what people most need to talk about. It is also the most rewarding part of what we do.
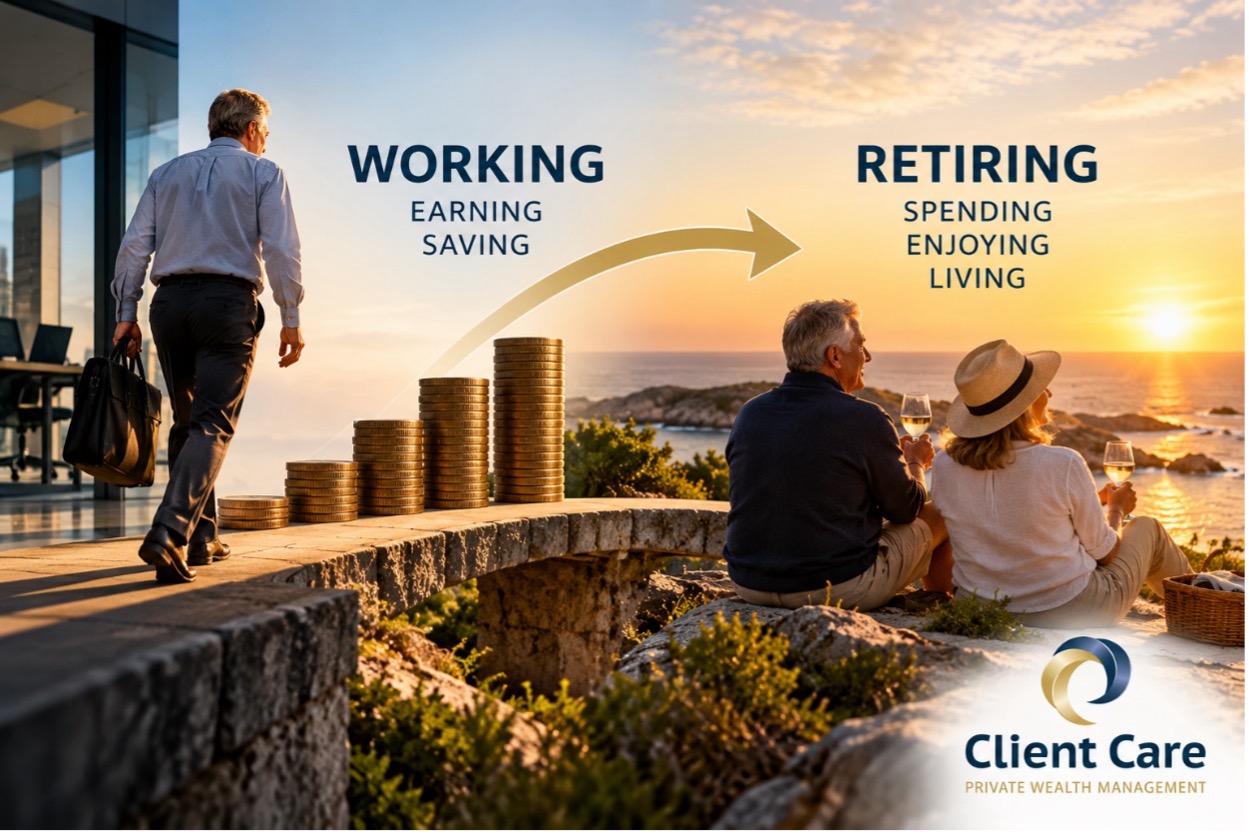
To be clear, this isn’t about being cavalier. It’s about doing the maths first, understanding what you can spend and still be okay in the long run, and then giving yourself permission to spend within those guidelines. Money is a tool for living our best life by design, not something to hoard because we don’t know what’s possible.
If you’re unsure whether you have enough, pop in for a chat. Let’s erase those fears and make sure the one life you live is one worth living.
—
Dirk Groeneveld, Certified Financial Planner
t. 083 261 9287
e. dirk@clientcare.co.za
An Investment Portfolio Without a Plan is Meaningless
Five Dangers Of DIY Financial Planning
Finding The Delicate Balance In Giving
Dead Money, Living Money
—

Disclaimer:
This article is for information purposes only and does not constitute financial advice in any way or form. It is important to consult a financial planner to receive financial advice before acting on any information contained herein. Client Care and PWM and its directors, officers, and employees shall not be responsible and disclaim all liability for any loss, damage (whether direct, indirect, special or consequential) and/or expense of any nature whatsoever, which may be suffered as a result of, or which may be attributable, directly or indirectly, to the use of, or reliance upon any information contained in this article.
by SFT | Sep 27, 2026 | Financial Planning, St Francis
I recently came across some research from Morningstar, presented by Ryan Murphy, their Global Head of Behavioural Insights. It asked a question I’ve been quietly thinking about for most of my thirty years in this profession: why do people actually hire a financial adviser?
The usual answer is a practical one. People come to us when retirement is getting closer, when an inheritance arrives, or when tax starts to feel complicated. Those are real reasons, but the research suggests they only tell part of the story.
Morningstar asked 623 households who already work with an adviser a simple, open question: “List some reasons why you hired your financial adviser.” They answered anonymously, which tends to bring out more honest answers than a question asked across a desk.
About a third of the answers were about specific needs, like planning for retirement or understanding tax. What struck me is that another third were about discomfort. People said things like “I don’t like making financial decisions” or “I don’t know enough to make the best choices.” Another 17% described what the industry calls behavioural coaching. One person admitted they lacked the discipline to stay invested when markets turned erratic. Another simply wanted “a sane voice” to bounce ideas off.
Put those together and most of the reasons were emotional, not technical.
This matters because other studies, including work by Vanguard, suggest that helping clients stay calm and stick to their plan can be one of the most valuable things an adviser does, sometimes adding more than 2% a year to returns. Most of that value comes from avoiding costly mistakes at the worst possible moment. Yet when people choose an adviser, it’s the thing they think about least.

Murphy compares it to broccoli and ice cream. Behavioural coaching is the broccoli: good for you, but nobody gets excited about it. Chasing returns is the ice cream. Interestingly, clients ranked “maximising my returns” lower than advisers assumed they would, and ranked feeling understood and well guided much higher.
None of this surprised me. The most important conversations I’ve had with clients were rarely about fund selection. They happened in 2008, in March 2020, and on ordinary days when someone simply needed to hear that the plan still made sense. Often the real work is listening, explaining things in plain language, and gently suggesting they leave things alone.

So if you’ve ever wondered what you’re really paying for, it’s partly the spreadsheets and the tax planning. But mostly it’s having someone beside you who knows your story, understands what matters to you, and helps you keep a steady hand when the world feels anything but steady.
That may be the broccoli, but it’s also the part that tends to make the biggest difference over time. If this has got you thinking, pop in for a coffee and a chat.
—
Dirk Groeneveld, Certified Financial Planner
t. 083 261 9287
e. dirk@clientcare.co.za
An Investment Portfolio Without a Plan is Meaningless
Five Dangers Of DIY Financial Planning
Finding The Delicate Balance In Giving
Dead Money, Living Money
—
Disclaimer:
This article is for information purposes only and does not constitute financial advice in any way or form. It is important to consult a financial planner to receive financial advice before acting on any information contained herein. Client Care and PWM and its directors, officers, and employees shall not be responsible and disclaim all liability for any loss, damage (whether direct, indirect, special or consequential) and/or expense of any nature whatsoever, which may be suffered as a result of, or which may be attributable, directly or indirectly, to the use of, or reliance upon any information contained in this article.
by SFT | Sep 20, 2026 | Financial Planning, St Francis
Most of us picture retirement as a list of things we’ll finally stop doing. No more early alarms, no more traffic, no more meetings that could have been a phone call. What we seldom picture is what quietly goes missing with them.
For decades, a job title does a lot of heavy lifting. At a braai, you say “I’m an engineer” or “I ran the practice,” and people know where to place you. Say “I’m retired,” and you’ve told them what you used to do, but very little about who you are now.
In over thirty years of sitting with clients, I’ve noticed something. People who say they miss work rarely miss the work itself. They miss what came with it: the routine, the colleagues, the quiet satisfaction of being good at something, and knowing someone was counting on them to show up. So when the phone rings less and the old office carries on perfectly well without them, a gentle question can surface; who am I now?

If that’s where you find yourself, please know it’s completely normal. It isn’t a sign that retirement has gone wrong. It’s simply part of settling into a new chapter. The good news is that you don’t need one grand purpose to replace your career. I’d suggest thinking about it the way we think about an investment portfolio. Your career was one very large holding. It supplied income, status, friendship and meaning all at once. That concentration served you well, but now it’s time to diversify.
Here in St Francis Bay, the options are right on our doorstep. You might become the grandparent who teaches the little ones to fish off the canals, a volunteer with one of our community organisations, a regular on the golf course, part of a morning walking group on the beach, or simply the neighbour who always knows whom to call. Some roles bring meaning, some bring friendship, and some just make a Wednesday more enjoyable. Together, they make a fuller life than any single title ever could.
Here’s a small exercise that could help you, finish this sentence:
“When I stop being known as ______, I’d like to spend more time being ______.”
Choose something active, then take one small step towards it this month.
And if you know someone who has made the transition gracefully, invite them for coffee at Bruce’s and ask what they missed most when they stopped working, and what eventually filled that gap.
You’ll likely leave with more than good advice. You’ll leave reassured.
—
Dirk Groeneveld, Certified Financial Planner
t. 083 261 9287
e. dirk@clientcare.co.za
An Investment Portfolio Without a Plan is Meaningless
Five Dangers Of DIY Financial Planning
Finding The Delicate Balance In Giving
Dead Money, Living Money
—
Disclaimer:
This article is for information purposes only and does not constitute financial advice in any way or form. It is important to consult a financial planner to receive financial advice before acting on any information contained herein. Client Care and PWM and its directors, officers, and employees shall not be responsible and disclaim all liability for any loss, damage (whether direct, indirect, special or consequential) and/or expense of any nature whatsoever, which may be suffered as a result of, or which may be attributable, directly or indirectly, to the use of, or reliance upon any information contained in this article.
by admin | Sep 6, 2026 | Financial Planning, St Francis
There’s a phone call I’ve come to recognise over thirty years in this profession. It starts with, “Dirk, I need your advice about my mother,” and within a few sentences I can tell we’re already behind. A diagnosis has come, capacity is fading, and the family is trying to work out in a hurry what can still be done.
Sometimes there’s still a good answer. But it’s never as simple as it would have been a year earlier. In South Africa, so much of what we can legally do depends on one thing: whether a person still has the mental capacity to decide. Once that’s gone, some doors close for good.
Why plan early? Acting while the mind is clear means wishes are recorded, finances are protected, and families know their options without the cost and stress of an emergency court application. I’ve sat with families going through that, and the emotional toll often outweighs the financial one.
Your options, in brief:
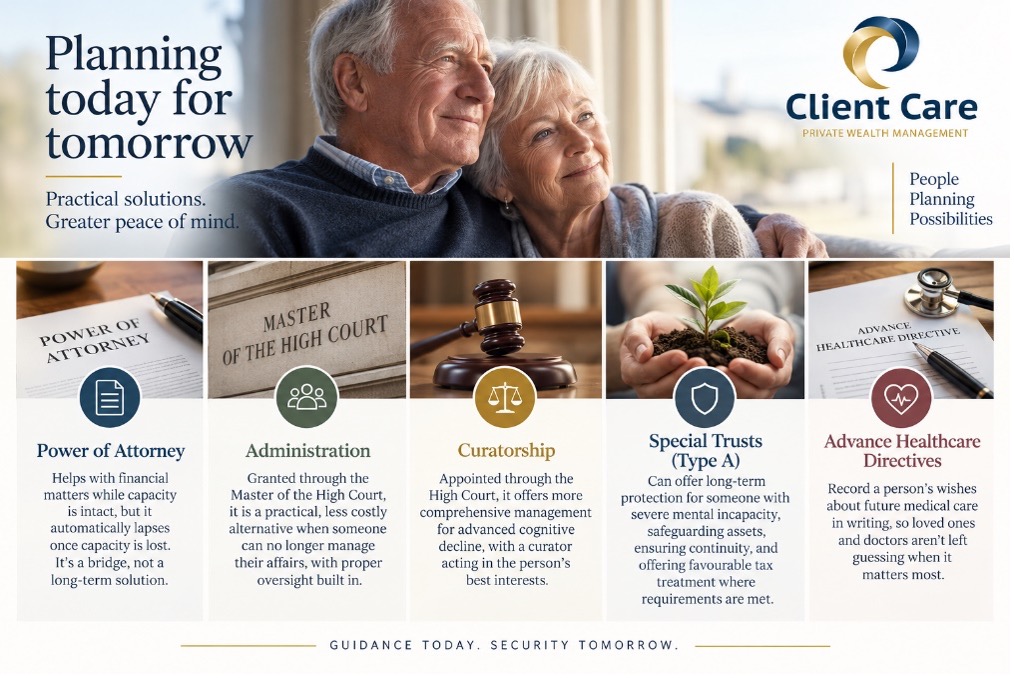
Power of Attorney helps with financial matters while capacity is intact, but it automatically lapses once capacity is lost. It’s a bridge, not a long-term solution.
Administration, granted through the Master of the High Court, is a practical, less costly alternative when someone can no longer manage their affairs with proper oversight built in.
Curatorship, appointed through the High Court, offers more comprehensive management for advanced cognitive decline, with a curator acting in the person’s best interests.
Special Trusts (Type A) can offer long-term protection for someone with severe mental incapacity and safeguarding assets, ensuring continuity, and offering favourable tax treatment where requirements are met.
Advance Healthcare Directives record a person’s wishes about future medical care in writing, so loved ones and doctors aren’t left guessing when it matters most.
Wills should be reviewed and signed while capacity still allows it, ideally well before any diagnosis, so they reflect current wishes rather than an outdated chapter of life.
Before the crisis, not during it
None of this is about taking control away from someone. Done at the right time, it’s one of the most respectful things a family can do, preserving a person’s own wishes in their own words, made by their own hand, while they were still able to decide.
A dementia diagnosis is hard enough without a family untangling legal and financial matters under pressure. If there’s one thing to take from this; have the conversation now, while it’s still just a conversation.
As always, at Client care we happy to talk this through with you or your family, whenever it feels right.
—
Dirk Groeneveld, Certified Financial Planner
t. 083 261 9287
e. dirk@clientcare.co.za
An Investment Portfolio Without a Plan is Meaningless
Five Dangers Of DIY Financial Planning
Finding The Delicate Balance In Giving
Dead Money, Living Money
—
Disclaimer:
This article is for information purposes only and does not constitute financial advice in any way or form. It is important to consult a financial planner to receive financial advice before acting on any information contained herein. Client Care and PWM and its directors, officers, and employees shall not be responsible and disclaim all liability for any loss, damage (whether direct, indirect, special or consequential) and/or expense of any nature whatsoever, which may be suffered as a result of, or which may be attributable, directly or indirectly, to the use of, or reliance upon any information contained in this article.
by SFT | Aug 24, 2026 | Financial Planning, St Francis
Retirement might sound fairly straightforward. Finish work, put away the alarm clock and start enjoying all that extra time. In reality, the transition can be considerably more complicated.
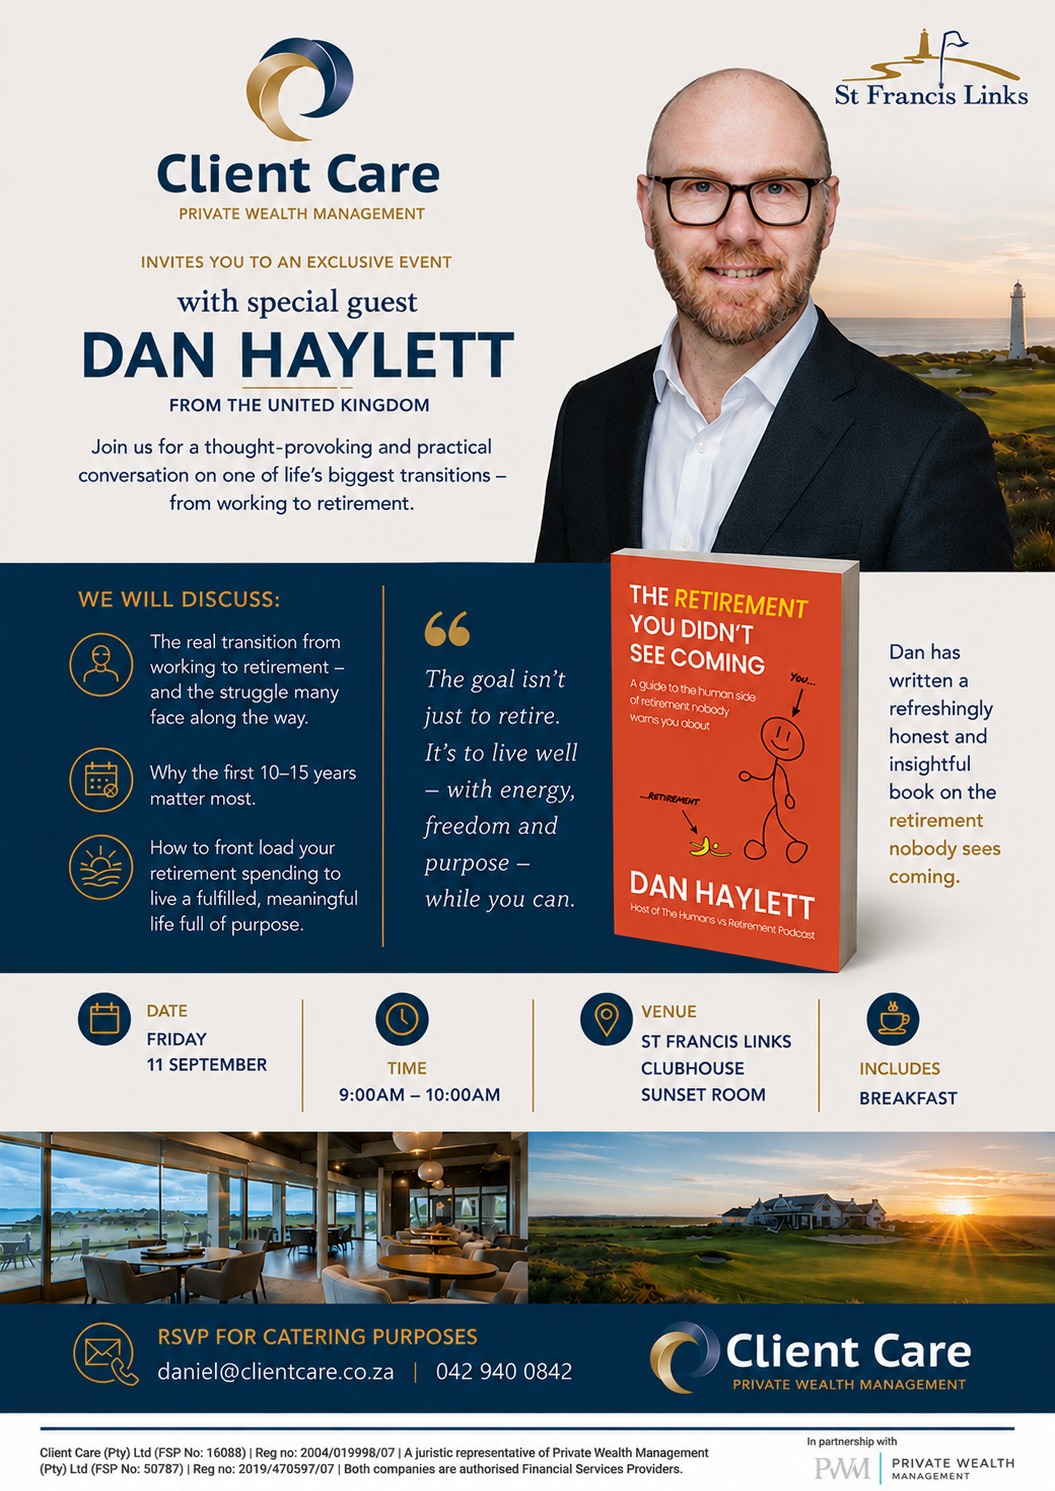
Client Care Private Wealth Management is hosting UK retirement specialist and author Dan Haylett at St Francis Links on Friday, 11 September, for a practical conversation about moving from working life into retirement.
Haylett is the author of The Retirement You Didn’t See Coming, a book exploring the human side of retirement and some of the challenges that arrive with one of life’s biggest transitions.
Living Well In Retirement
The discussion will look beyond the financial mechanics of retirement and focus on how people actually live once their working years come to an end.
Haylett will explore why the first 10 to 15 years of retirement can be particularly important. He will also discuss the concept of “front-loading” retirement spending, allowing people to make greater use of their money during the years when they have the energy and freedom to enjoy it.
As Haylett puts it, the goal is to retire and “live well – with energy, freedom and purpose – while you can.”
Breakfast At St Francis Links
The event takes place in the Sunset Room at the St Francis Links Clubhouse from 9am to 10am and includes breakfast.
Attendance is by RSVP for catering purposes. Those interested can book here – https://clientcare.co.za/events/ or contact Client Care at daniel@clientcare.co.za or call 042 940 0842.
For anyone approaching retirement, already retired, or simply thinking a little further down the road, it promises to be an interesting hour exploring what life after work can actually look like.


Recent Comments