
A few weeks ago, we at Client Care hosted a breakfast with my good friend Dan Haylett, a financial planner from London. Dan and I share a passion for helping clients live a full and meaningful retirement. He has written a book on the subject and has just been commissioned by a major European publisher to write another. Our conversation centred on something we both believe needs far more airtime: the tough move from working to retiring, and from saving to spending.
After decades of diligent saving, many retirees find it remarkably hard to switch gears. Where we differ from many advisers is that we encourage our clients to spend their savings rather than hoard them out of fear of running out.

Participation was wonderful, and the range of responses fascinated me, from a sense of helplessness to raw excitement.
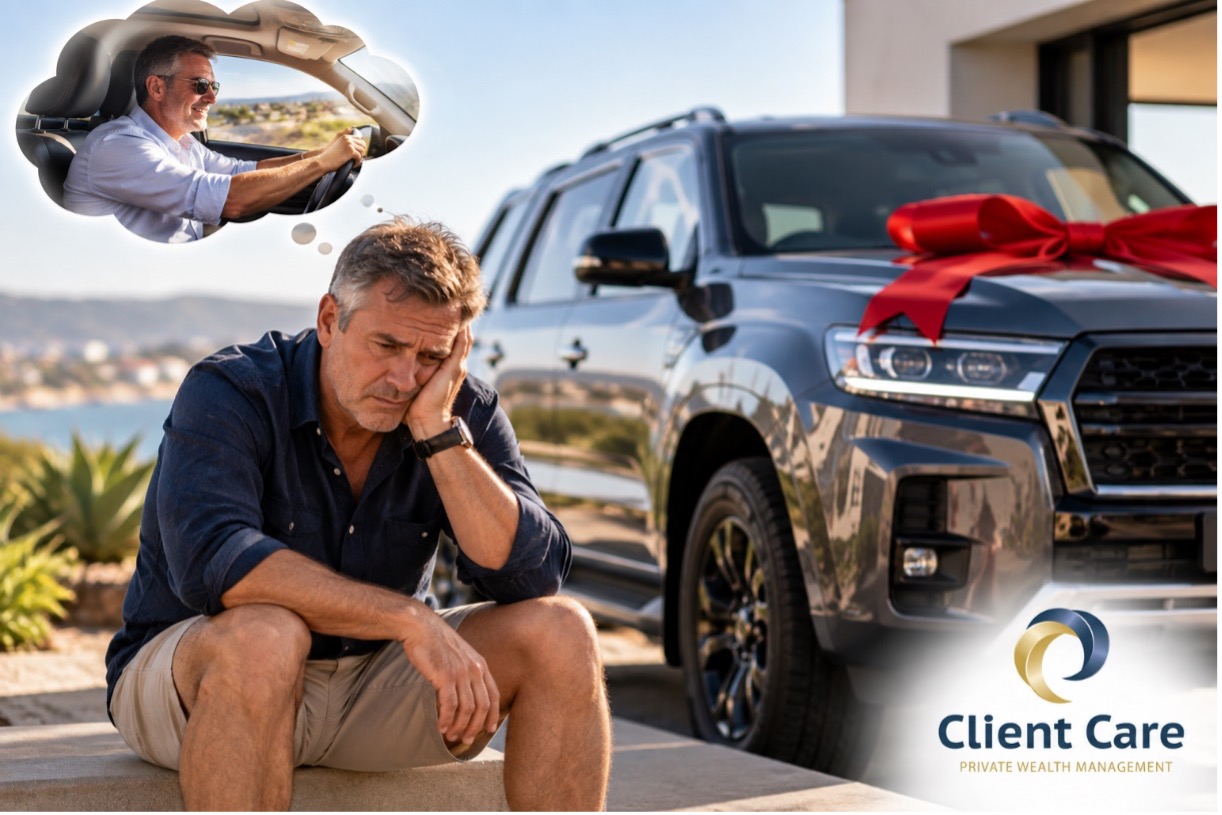
Returning from a few weeks out of town, I chatted with some friends who had attended. One was blown away to hear two financial planners advocating spending, especially as a planner’s income is often linked to the assets we advise on. He had been nursing a little buyer’s remorse over a new car, but after the talk felt completely at peace with it, and even topped up the family holiday account for the children and grandchildren.
Another had recently skipped a family get-together at a wine farm, worried about what the day would cost him. He regrets it now, and says he won’t make that mistake again.
Then there was the wife of a client retiring in a few months. She came over with a smile and told me I had my work cut out shifting her husband out of the saving mindset, the very habit that has allowed them to retire so comfortably.
I’ll admit I was a little nervous building a talk around the soft stuff rather than markets and tax strategies. The response has shown me that the soft stuff is actually the hard stuff, and it’s what people most need to talk about. It is also the most rewarding part of what we do.
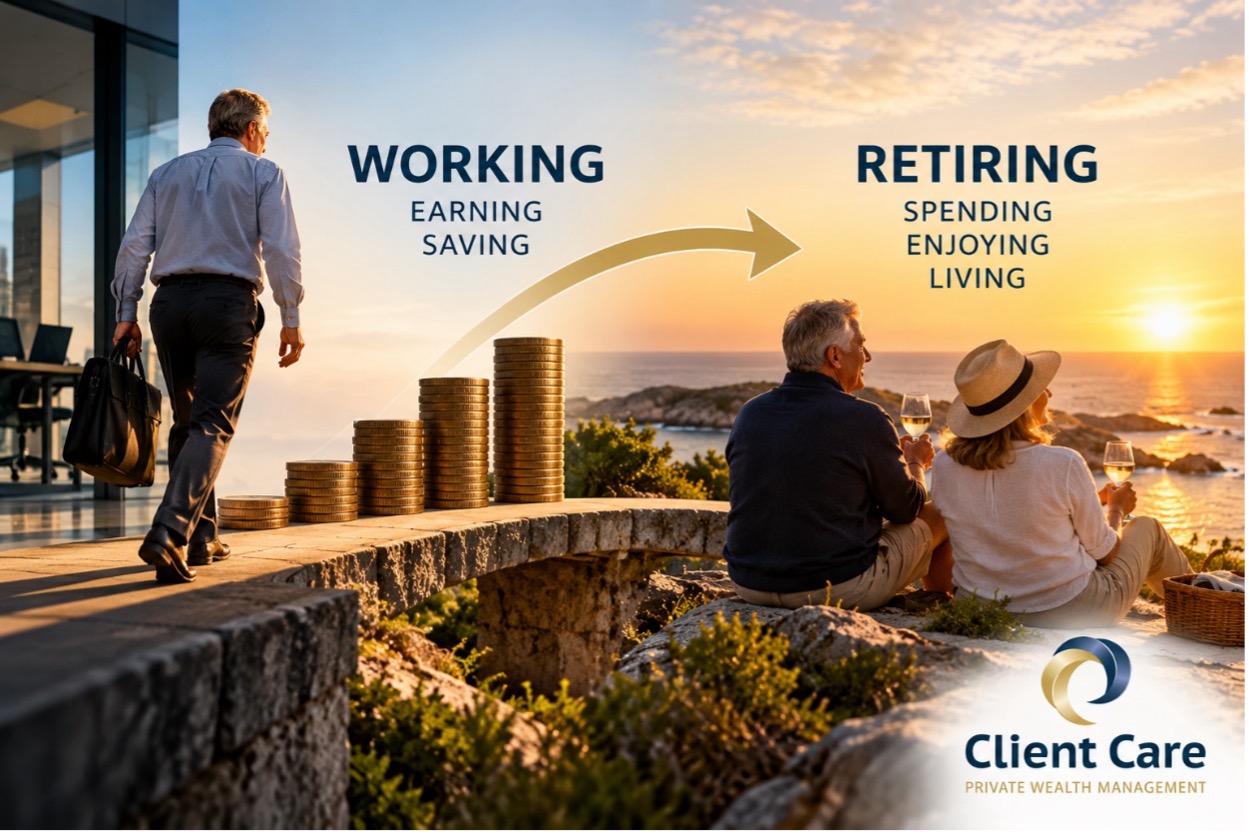
To be clear, this isn’t about being cavalier. It’s about doing the maths first, understanding what you can spend and still be okay in the long run, and then giving yourself permission to spend within those guidelines. Money is a tool for living our best life by design, not something to hoard because we don’t know what’s possible.
If you’re unsure whether you have enough, pop in for a chat. Let’s erase those fears and make sure the one life you live is one worth living.
—
Dirk Groeneveld, Certified Financial Planner
t. 083 261 9287
Recent Columns
An Investment Portfolio Without a Plan is Meaningless
Five Dangers Of DIY Financial Planning
Finding The Delicate Balance In Giving
—

Disclaimer:
This article is for information purposes only and does not constitute financial advice in any way or form. It is important to consult a financial planner to receive financial advice before acting on any information contained herein. Client Care and PWM and its directors, officers, and employees shall not be responsible and disclaim all liability for any loss, damage (whether direct, indirect, special or consequential) and/or expense of any nature whatsoever, which may be suffered as a result of, or which may be attributable, directly or indirectly, to the use of, or reliance upon any information contained in this article.

Recent Comments